Christmas on the Installment Plan: The Layaway Counter Was America's Quiet Holiday Lender
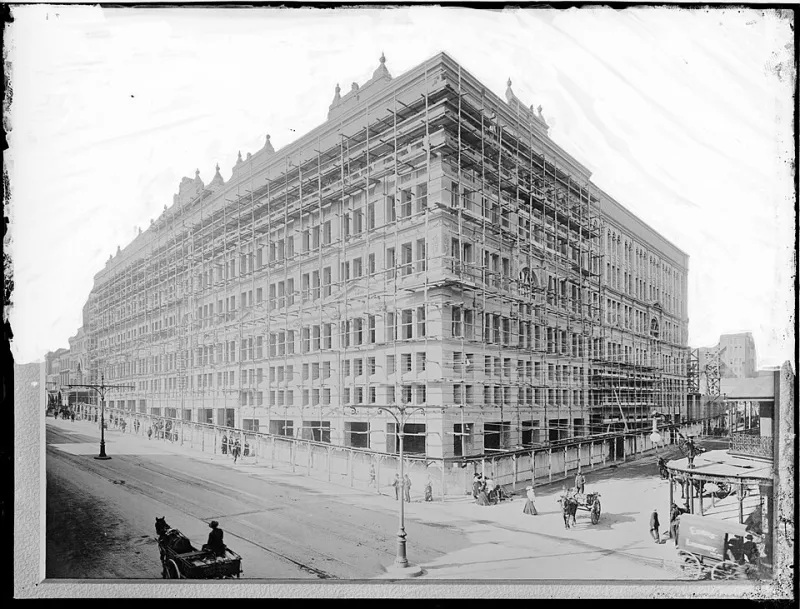
Photo: Arthur Ernest Foster, Public domain, via Wikimedia Commons
Every September, a certain kind of American parent began making weekly trips to the department store. They did not go to browse. They went to the layaway counter, a service desk tucked near the back of the store, and handed over a few dollars against a bicycle or a dollhouse that would stay in storage until December. The store kept the merchandise. The family kept a receipt. Christmas had begun, quietly, three months early.
Layaway was never glamorous. It was a budget tool for people who did not have credit cards, or did not trust themselves with them. It was also a way to protect a surprise. The gifts were not hidden in a closet at home, where a curious eight-year-old might find them. They were hidden in the store, behind a counter, waiting for the final payment.
The Counter Behind the Toy Aisle
The mechanics were simple. You chose an item, paid a down payment, and signed an agreement. The store set it aside. Every week or every payday, you came back and paid a little more. There was usually a small service fee. If you missed too many payments, the store canceled the layaway and refunded your money, minus the fee. You did not get the item until you paid it off. That was the whole point.
Sears, Kmart, Walmart, and countless local department stores all ran layaway programs. For many families, the counter was a familiar part of the holiday season, as predictable as the Sears Wish Book. It had a social dimension, too. The clerk behind the counter knew which families were close to paying off the bike and which ones were struggling. There was no credit score involved. There was just a handwritten slip and a promise.
Layaway faded in the 1990s and 2000s as credit cards became easier to get and stores decided the counter was not worth the staff time. Then it came back. The 2008 recession brought layaway back to Walmart and other retailers, and the pandemic gave it another small revival. The appeal was obvious: no interest, no credit check, no debt hanging over January.
Swipe Now, Pay Later
The modern alternative is buy now, pay later. Apps like Afterpay, Klarna, and Affirm let you split a purchase into four payments, often at checkout, often in seconds. There is no counter and no clerk. There is a soft credit check, a payment schedule, and a late fee if you miss a installment. The item ships immediately. You do not have to wait until Christmas.
That immediacy is the biggest difference. Layaway was a commitment device built on delay. The store held the item, which meant you could not take it home and give it early. BNPL is built on speed. You get the thing now, and the payments follow you. For a disciplined shopper, that can be convenient. For an impulsive one, it can turn a single purchase into four small decisions.
The fees are different, too. Layaway charged a service fee, but it did not charge interest. BNPL is often interest-free if you pay on time, but late fees and missed payments can add up. Neither system is free. One charges you for the store's storage and paperwork. The other charges you for the privilege of not waiting.
What the Receipt Meant
There was something clarifying about a layaway slip. It told you exactly how much you still owed and exactly when the item would be yours. You could fold it into your wallet and check it on a Friday night. The payment was not abstract. It was a small ceremony that moved Christmas a little closer.
Today's confirmation email does the same job, but it feels less like a promise and more like a receipt. The item is already on its way. The payments are automatic. The discipline has been outsourced to an app.
Maybe that is progress. Layaway could be humiliating, and it tied up money for months. BNPL is faster and more private. But the old counter taught a specific lesson: some things are worth waiting for, and a small weekly payment is a way of saying so. The new apps have removed the wait. It is not clear they have replaced the lesson.